All Categories
Featured
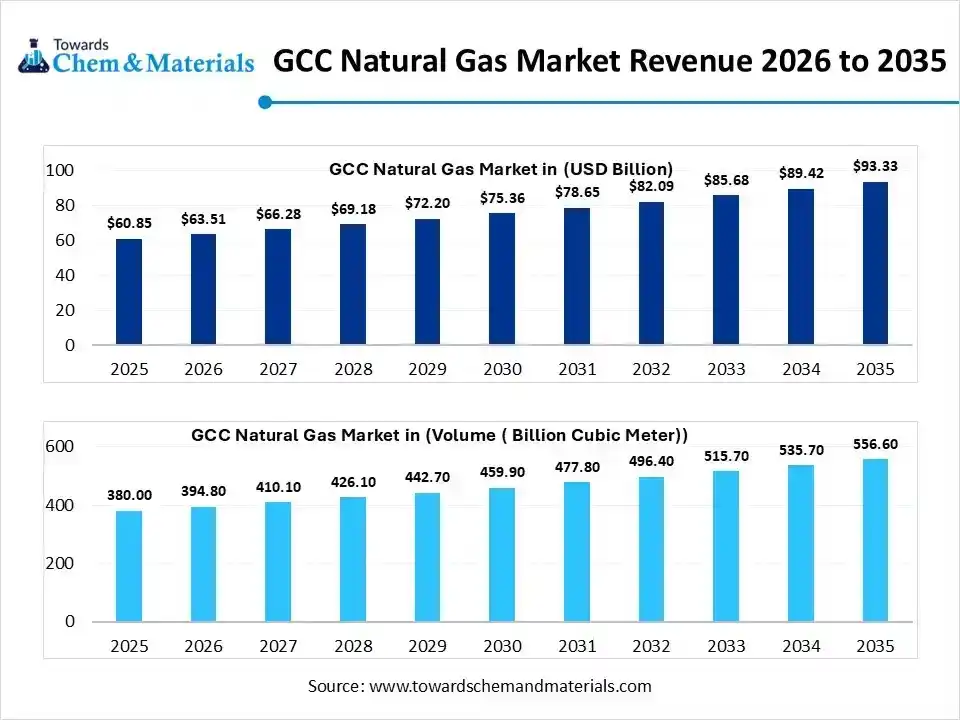
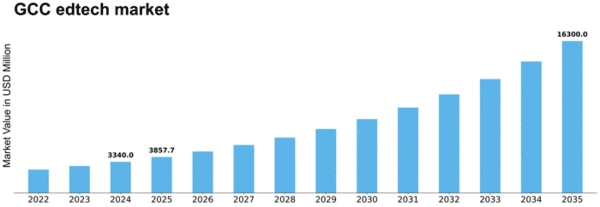
Evaluating Traditional Models and Future Business Frameworks
Instead of marking a cyclical rebound, 2026 is increasingly considered as a consolidation year, in which diversification-led development becomes more deeply ingrained in the region's financial design, reducing reliance on hydrocarbons and increasing resilience to external shocks. Forecasts from major organizations broadly assemble on a more powerful GCC growth profile in 2026 than in 2025, supported by durable domestic demand, continued non-oil expansion, and (to varying degrees) a firmer hydrocarbon contribution.
3.2 percent development in 2025, accelerating to 4.5 percent in 2026. Sees momentum improving, with GCC output development forecasted to rise from 1.7 percent in 2024 to 3.3 percent on average in 2025, reflecting a shift toward more positive overall conditions.
Driving Regional Industrial Growth through Strategic ExcellenceThe IMF's World Economic Outlook (October 2025) jobs worldwide development easing to 3.1 percent in 2026, with innovative economies around 1.5 percent and emerging market and developing economies simply above 4 percent. On that contrast, a 4.44.5 percent GCC expansion would put the area materially ahead of the world average and a little above (or broadly in line with) the emerging-market aggregate, strengthening the GCC's status as a relatively high-growth pocketprovided that regional threat conditions remain contained and reform momentum holds.
How to Implement Advanced Strategies in 2026Data from the GCC Statistical Center reveal that non-oil sectors already represent more than 73 percent of total GDP, a share that has actually continued to rise as federal governments broaden investment in services, infrastructure, and technology. According to Oxford Economics, non-energy activity across the GCC is projected to grow by around 4.1 percent in 2026, supported by strong labor markets, improving credit conditions, and rising financial investment in technology and AI-related infrastructure.
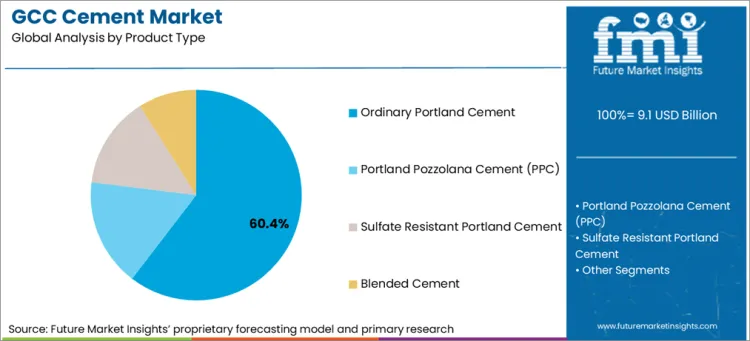
Accelerating Regional Corporate Expansion through Strategy
Public-sector investment and reform stay central to sustaining this trend. Policy measures aimed at drawing in foreign direct financial investment, easing foreign ownership guidelines, expanding capital markets, and supporting private-sector involvement continue to underpin non-oil expansion and minimize the region's exposure to oil cost volatility. While hydrocarbons no longer control the development outlook, oil earnings are expected to play an encouraging function in 2026.
Oxford Economics anticipates Brent crude costs to fall listed below USD 60 per barrel in early 2026, limiting the near-term contribution of oil extraction to GDP. Oil supply is anticipated to increase again in the 2nd half of the year, with a full unwinding of staying production caps most likely by mid-2027.
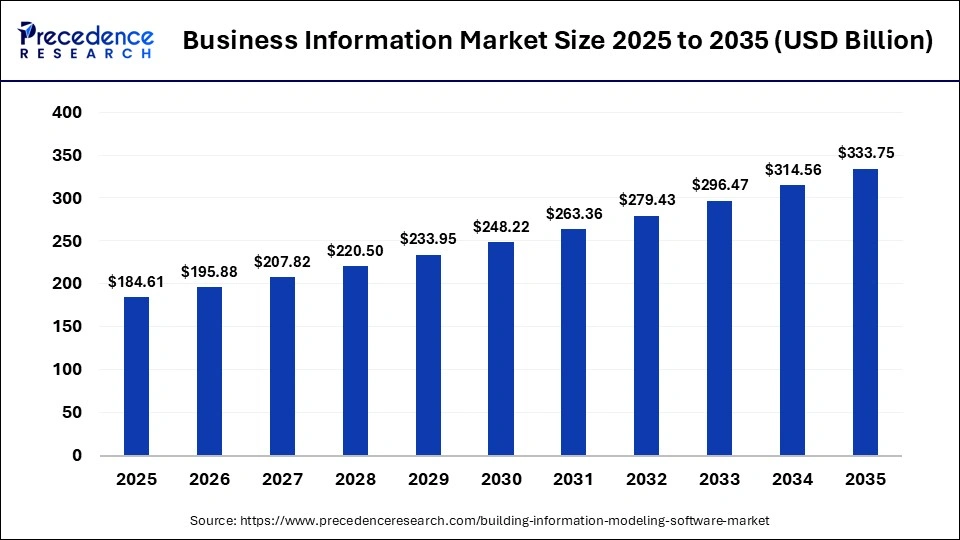
Macroeconomic conditions throughout the GCC remain broadly supportive of growth. Inflation is anticipated to stay low, with the IMF forecasting average inflation of 2 percent throughout the area in 2026. Steady rates are assisting maintain genuine household earnings and underpin customer costs, which Oxford Economics anticipates to grow by approximately 3.5 percent over 20262027.

Latest Posts
Why Is Business Excellence Crucial for Future Growth?
Key GCC Market Research Insights for 2026
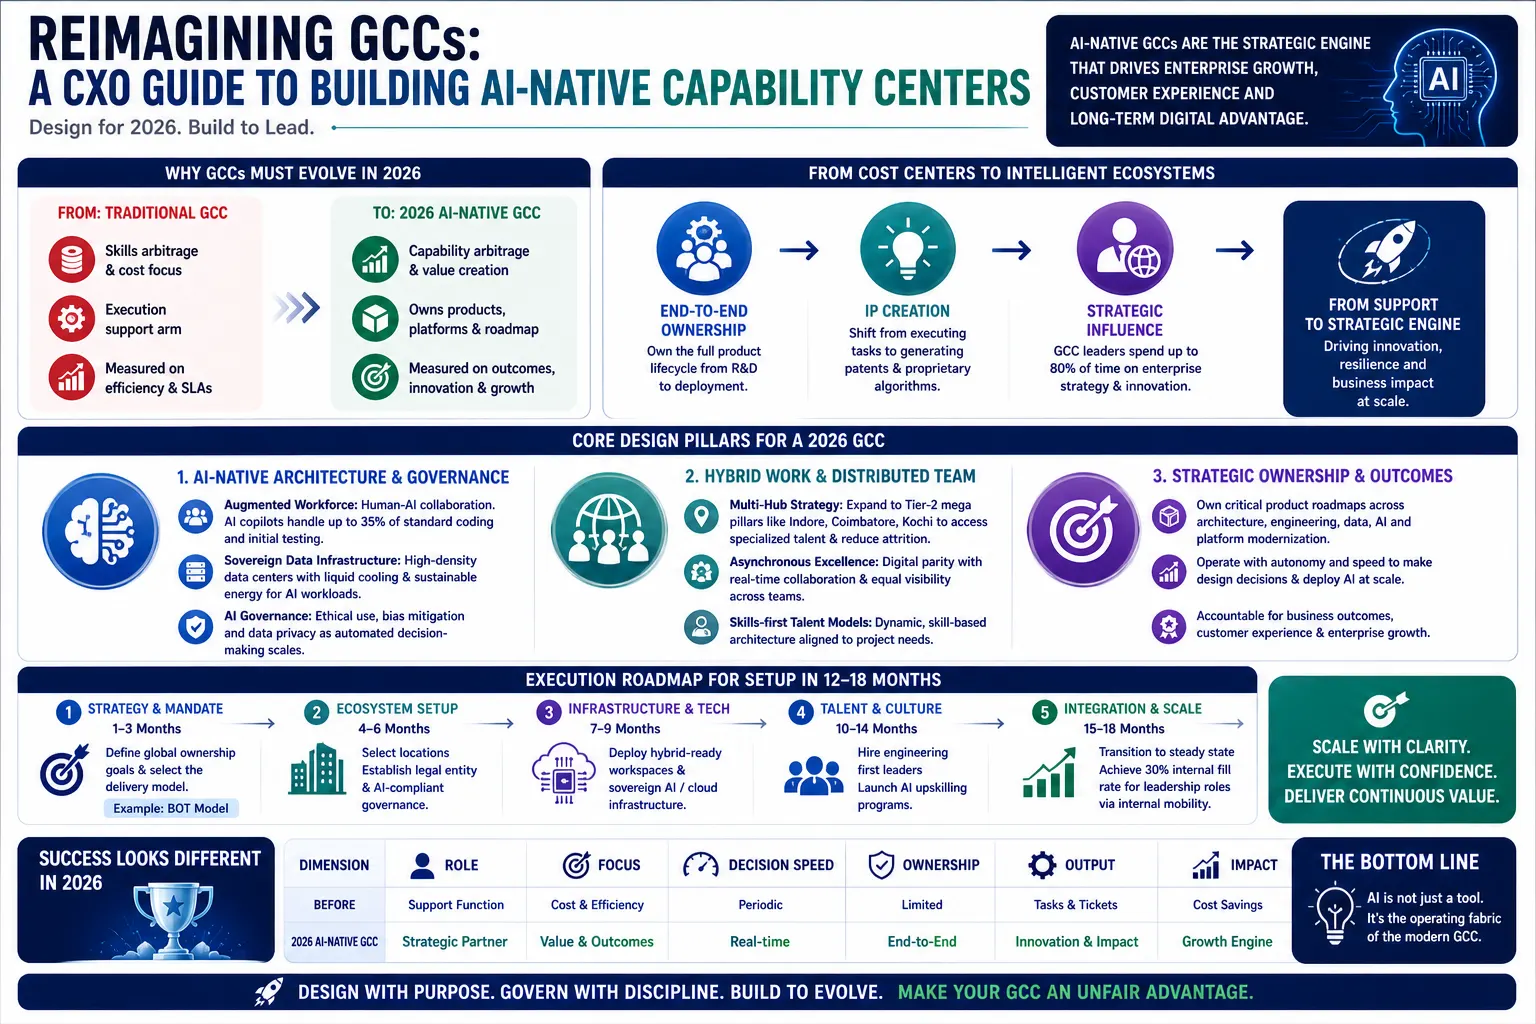
Scaling Corporate Growth Through Operational Innovation